
Taxes, Giving, and How to Make Uncle Sam a Little Less Expensive
Taxes, taxes, taxes…
“In this world, nothing can be said to be certain, except death and taxes.”
Benjamin Franklin said it more than 200 years ago, and the sentiment remains true today. While taxes may be unavoidable, can we at least make them a little less painful?
Absolutely.
The internet is filled with articles about taxes, tax strategies, retirement planning, charitable giving and countless acronyms designed to simplify an already complicated subject.
The truth is, financial planning shouldn't feel like you're reading a foreign language. A big part of our job as advisors is taking complicated topics, breaking them down into plain English and helping you understand your options.
One strategy that can be particularly useful for retirees who are charitably inclined is the Qualified Charitable Distribution, or QCD.
You May Be More Charitable Than You Think
When I say “charitably inclined,” you might picture someone writing a large check to their favorite nonprofit. But charitable giving can take many forms.
Maybe you donate to your church.
Maybe you support your child's school.
Maybe you contribute to a scholarship program.
Maybe you give to a local nonprofit, food bank or community organization.
These individual gifts may not feel like significant financial decisions, but collectively, they can add up to a meaningful amount over the course of a year. For retirees, charitable giving can also intersect with retirement income and tax planning, particularly once required minimum distributions begin.
What Happens When You Turn to RMD age?
One question we hear often from retirees is:
“I'm turning 73 (or 75), and I have to start taking money out of my IRA. I'm not sure I need the money. If I have to take it, does that mean I have to pay taxes on it?”
Unfortunately, yes. That's the basic idea behind a Required Minimum Distribution, or RMD.
A RMD is an amount that the IRS requires individuals to withdraw each year from certain retirement accounts once they reach their applicable RMD age. For individuals who do not need the funds to cover their living expenses, an RMD can create additional taxable income.
This raises an important planning question: If the money is not needed for living expenses and the individual is already making charitable contributions, is there a more tax-efficient way to distribute those funds?
For those who are charitably inclined, a QCD may be worth considering.
What Is a QCD?
A Qualified Charitable Distribution is a way for someone who is at least 70½ years old to send money directly from their IRA to an eligible charity.
It’s great because the amount sent directly to charity can satisfy part or all of your RMD and generally isn't included in your taxable income.
Instead of: IRA → You → Charity
you can potentially do: IRA → Charity -> Left over IRA to you
The money still leaves your IRA, but instead of first landing in your bank account and becoming taxable income, the qualifying amount goes directly to the charity.
Who Can Do This?
There are a few important rules:
You must be at least 70½ years old.
The distribution must generally go directly from your IRA to an eligible charity.
The QCD limit for 2026 is $111,000 per person.
The charity must be an eligible organization under the IRS rules.
And importantly, a QCD isn't available from every type of retirement account. For example, QCDs generally apply to IRAs, not 401(k)s or 403(b)s. As always with taxes, there are rules hiding in the bushes, so it's worth confirming the details with your advisor and CPA.
Let's Put Some Numbers Behind It
Let's say you’re married with gross income around $200k and your RMD for the year is $17,306. But let's say you planned to give $1,500 to charity anyway.
Option 1: Take the full RMD as income
Taxable income: $17,306
You pay full federal and California tax on this amount
Option 2: Give $1,500 directly to charity (QCD)
Taxable income: $15,806
The $1,500 goes to charity and is not taxed
What this saves you on the $1,500 gift:
Federal tax savings (22%): about $330
California tax savings (~9%): about $135
Total tax savings: about $465
In simple terms:
It’s a way to both give and reduce taxes, without adding much complexity.
You give $1,500 to a charity you care about, and it only “costs” you about $1,035 after tax savings. The actual tax savings will of course depend on your individual tax situation and marginal tax brackets.
How Do You Make a QCD?
Understanding a strategy is only part of the process. Proper implementation is equally important.
If you are taking an RMD and regularly make charitable contributions, consider discussing QCDs with your financial advisor early in the year. You can simply say:
“I know I'm taking an RMD this year, and I'd like to make some charitable gifts. Can we look at doing those as QCDs?”
From there, your advisory team can help coordinate the process.
You'll generally want to provide the charities you're planning to support, along with their addresses and, if available, their tax identification information.
And then comes an important housekeeping item: Don't accidentally give twice.
One practical consideration is to review your existing charitable giving arrangements. If you regularly make charitable donations using a credit card or automatic payment, account for those contributions when determining how much you intend to give through QCDs.
What If You Like to Give Spontaneously?
Not everyone plans their charitable giving at the beginning of the year. Some individuals prefer to make contributions as opportunities arise. Maybe you see a local organization doing something great and think:
“I want to help.”
That's okay, too.
Certain IRA custodians allow IRA owners to have check-writing privileges on their accounts, which may provide additional flexibility for charitable giving throughout the year. However, the applicable QCD requirements must still be satisfied, and appropriate records should be maintained.
If you prefer to give throughout the year, discuss your options with your financial advisor or IRA custodian.
What About My Tax Return?
This is another area where QCDs can seem confusing.
If you are curious, this is how it will look when you file your taxes - assuming your RMD for the year is $50k and you decided to give half of that as a QCD. As you can see in the example image, line 4a is where any amount which was distributed from your IRA will be placed, but if you give to charity, line 4b is reduced by that amount.
Line 4a = total distribution
Line 4b = taxable portion (after any charitable giving)
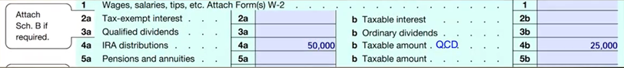
It’s line 4b that flows into the rest of your return and determines how much tax you actually owe. So even though you took the full distribution, you’re only taxed on the reduced amount.
This is an area where communication between your financial advisor, IRA custodian and CPA is important to ensure the transaction is reported correctly.
There's Another Potential Benefit: Medicare
For some retirees, higher income can also affect Medicare premiums through IRMAA, the income-related adjustment that can cause Medicare Part B and Part D premiums to increase.
Because a QCD can reduce the amount of an IRA distribution that counts toward taxable income, it may also help reduce the income Medicare uses when determining IRMAA, depending on your overall tax situation.
This is one reason financial planning is best viewed as an interconnected process rather than as a series of separate decisions.
Your retirement account affects your taxes.
Your taxes can affect Medicare premiums.
Your charitable giving can affect how much of your retirement distribution is taxable.
And suddenly, what looked like a simple “I want to give $1,500 to charity” decision becomes part of a much bigger financial planning conversation.
So What's the Big Takeaway?
A QCD isn't the right strategy for everyone. However, if you are over 70½, have an IRA, are required to take RMDs and regularly make charitable contributions, it is worth discussing whether a QCD could make sense for your situation.
You were planning to donate regardless and so the question is:
Does it make more sense for that money to travel directly from your IRA to the charity rather than taking a detour through your bank account first?
That's where good planning comes in.
Taxes may be certain. But paying more than you need to isn't necessary.
So give generously, plan thoughtfully, work with your team and, most importantly…
Don't forget to enjoy some of your money while you're here.
After all, we're talking about gifting today and there's no reason you can't enjoy the present, too (pun intended).

About the Author
Marcelle Kako, CFP® is a Financial Advisor with Financial Alternatives. Marcelle is passionate about financial literacy, client education, and helping individuals build a strong foundation for long-term financial success. Outside of work, she enjoys travel, language learning, philosophy, literature, Pilates, and running. Learn more about our Wealth Management Services or contact our team to discuss your financial goals and planning opportunities.